What Is an RIA? A Plain-Language Guide to Registered Investment Advisers
“RIA” gets used constantly in financial advisor marketing, often without much explanation of what it actually means. Here’s a straightforward answer: a Registered Investment Adviser is a firm registered with the SEC or a state securities regulator, held to a fiduciary standard, legally required to act in an ongoing client’s best interest. That single distinction, fiduciary duty, is the reason the term matters at all.
What “RIA” actually stands for and means
A Registered Investment Adviser is a firm that provides investment advice and is registered with either the SEC or a state regulator, depending on the firm’s size and the states it operates in. Registration itself involves regulatory oversight, disclosure requirements, and ongoing compliance obligations. But the defining feature of an RIA isn’t the registration paperwork, it’s the fiduciary standard that comes with it: an RIA is legally required to act in its clients’ best interest on an ongoing basis, not simply to recommend something suitable. That fiduciary duty has two parts: a duty of care, meaning advice based on a reasonable understanding of the client’s situation and goals, and a duty of loyalty, meaning the adviser may not put its own interests ahead of the client’s and must either eliminate conflicts of interest or disclose them fully and fairly so the client can make an informed decision.
How an RIA differs from a broker-dealer
Broker-dealers, often the more familiar, larger-brand names in financial services, have traditionally operated under a different standard, suitability rather than fiduciary duty. Since 2020, they’ve been subject to Regulation Best Interest (Reg BI) when making recommendations to retail customers, which narrowed the gap. Real differences remain: an RIA’s fiduciary duty is ongoing and covers the entire advisory relationship, while Reg BI applies at the time of each recommendation, and a broker-dealer generally has no duty to monitor an account afterward unless it agrees to. A suitability standard, which still applies to some insurance products, allows a recommendation that’s appropriate for a client’s situation, even if a better, lower-cost, or lower-commission alternative exists. A fiduciary standard doesn’t allow an advisor to put their own interests ahead of the client’s;, the recommendation has to be in the client’s best interest, not just an acceptable one. Some firms and individuals are dually registered, acting as a fiduciary in their advisory role and under Reg BI in their brokerage role,, which is exactly why it’s worth asking directly which standard applies to a given relationship rather than assuming based on how a firm is described in its marketing.
How RIAs are typically compensated
RIAs are commonly compensated through fees, a percentage of assets under management, a flat planning fee, or an hourly rate, rather than commissions on products sold. That structure is often described as reducing certain conflicts of interest, since compensation isn’t tied to which specific product gets recommended. It’s worth noting this isn’t absolute: some RIAs, including firms with insurance or other affiliated licenses, may have additional compensation sources beyond the advisory fee, which is exactly the kind of detail worth asking about directly rather than assuming based on the RIA structure alone.
See how Apriem Advisors is compensated.
What to look for when choosing an RIA
A few things matter beyond the RIA designation itself:
- Confirm which services fall under the fiduciary standard.
- Understand the full compensation structure, including any sources of revenue beyond the advisory fee itself.
- Look at the firm’s actual experience with situations like yours, retirement transitions, business sales, multi-generational planning, rather than assuming all RIAs offer the same expertise.
- Ask about continuity, whether the same advisor stays with you over time, or whether client relationships get reassigned as a firm grows.
Questions worth asking before you commit
- Will you act as a fiduciary at all times with me?
- How are you compensated, in full, including any sources beyond an advisory fee?
- What’s your experience with situations similar to mine?
- Will the same advisor work with me over the long term, or does that change as the relationship continues?
- More items to look for and ask about when choosing an RIA or financial advisor.
Where Apriem fits
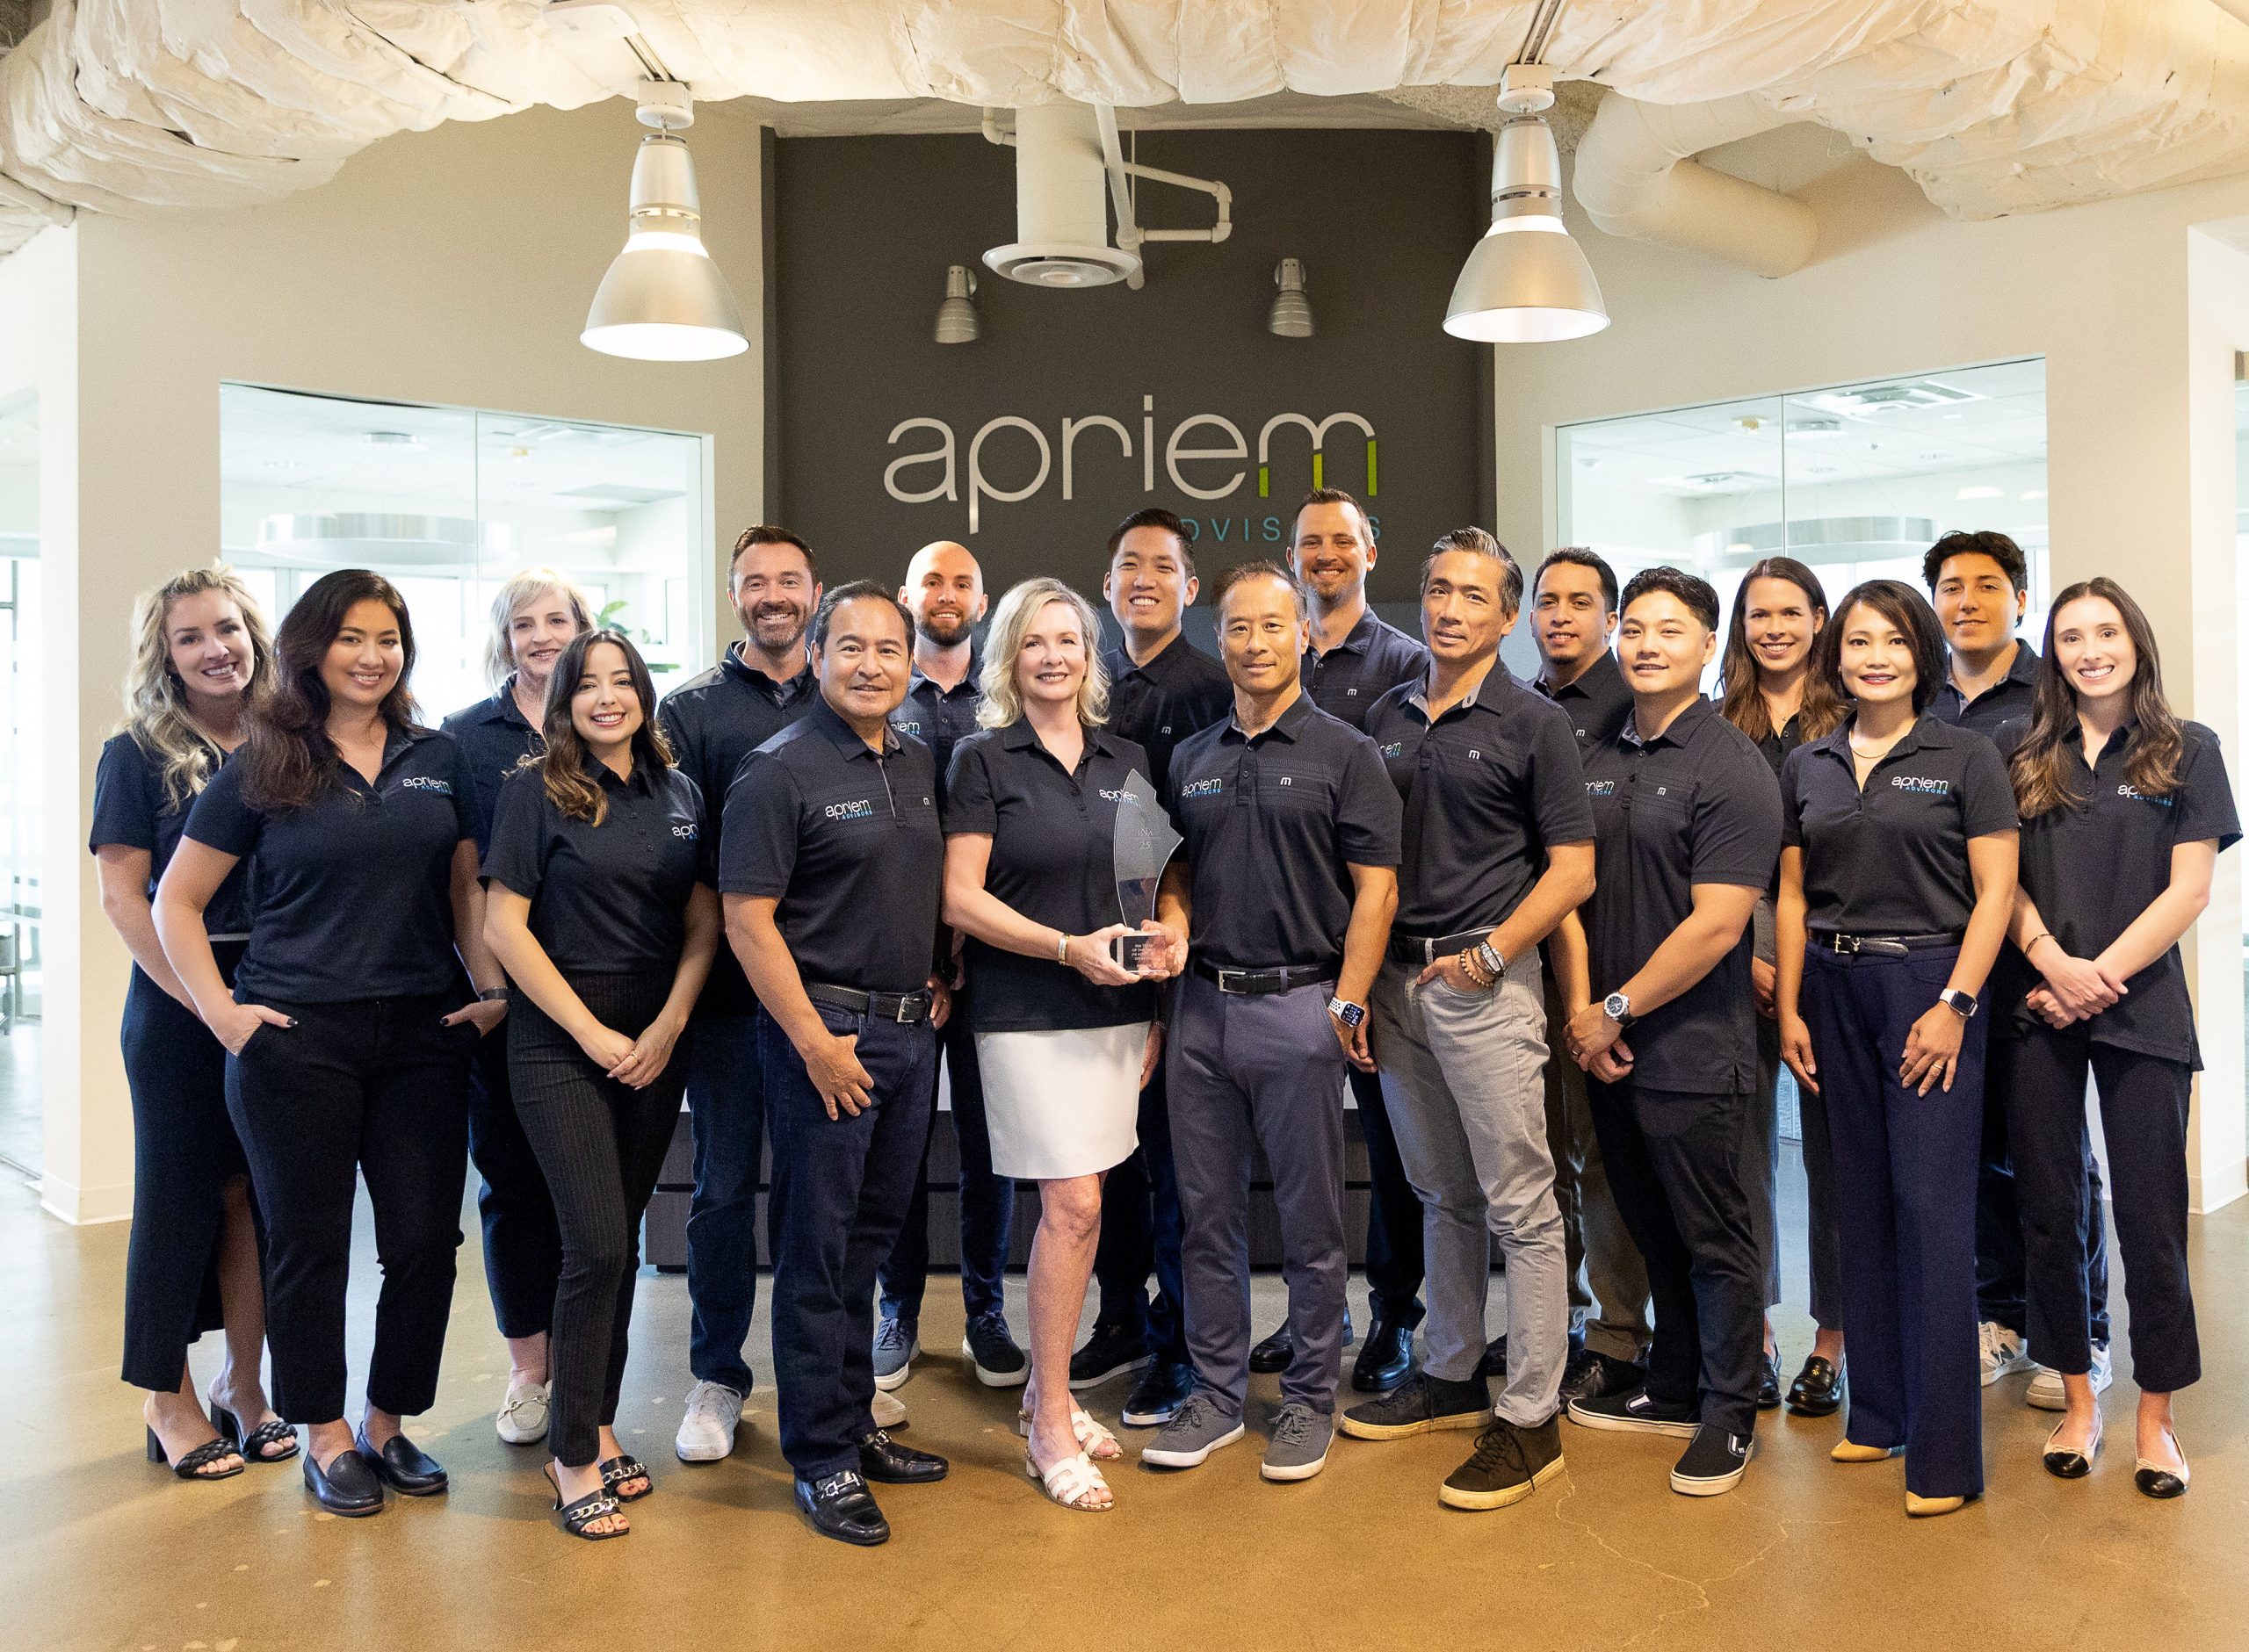
Apriem is an independent, fiduciary Registered Investment Adviser based in Irvine, California, coordinating investment management, tax planning, and estate planning as one ongoing relationship. Apriem has operated under this fiduciary structure for more than 28 years, currently works with more than 1,000 households, and has maintained a client retention rate above 99%*.
Have a question about how this applies to your own search for an advisor?
Disclosures
*As of 7/14/26. Client retention rate above 99% for the year-to-date period ending July 14, 2026.